Plymouth Property Taxes and Assessments Explained
Find Plymouth tax records, distinguish assessed and taxable values, check special assessments, and match each figure to the correct year.

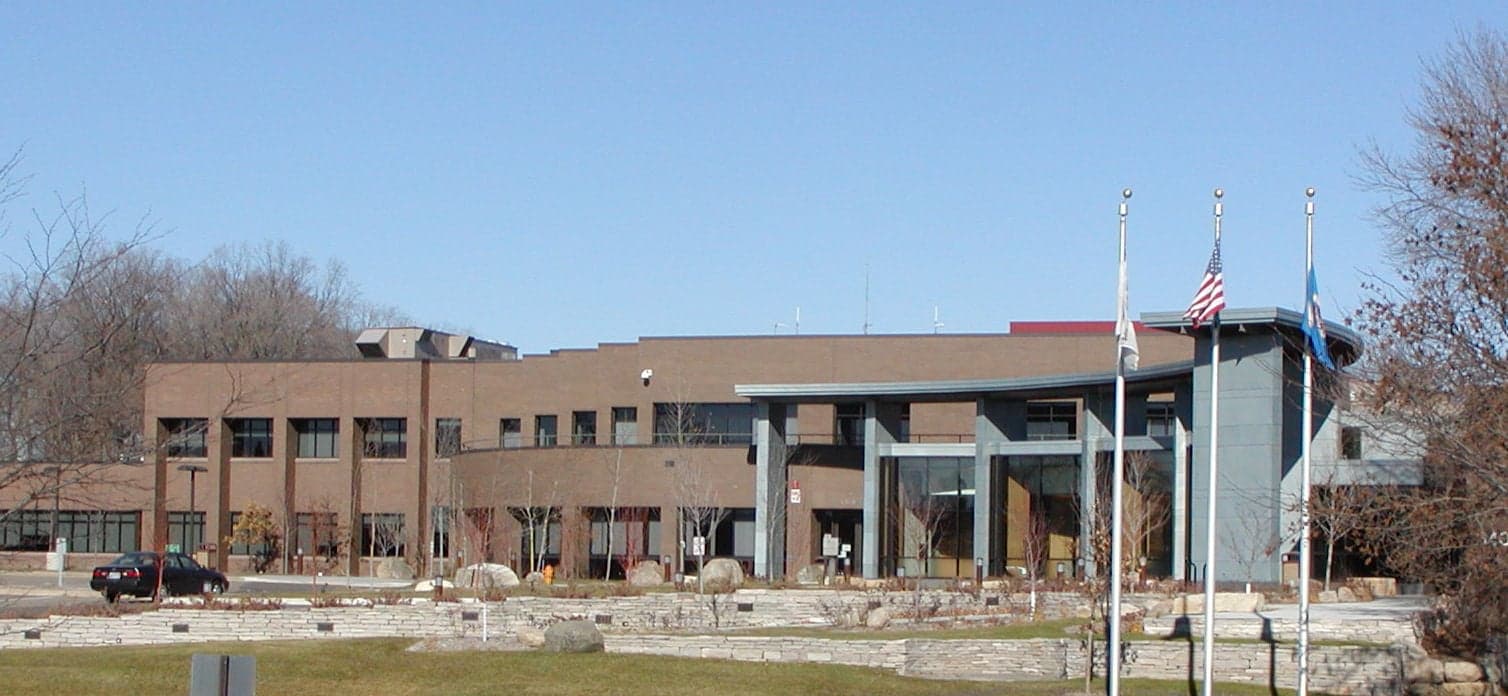
Plymouth City Hall exterior with three flagpoles, photographed in November 2006
Photo: William Wesen · Public domainStart a Plymouth property-tax review with the parcel number and three records: the tax statement, valuation notice, and city special-assessment information. Each answers a different question. This guide explains how to read them together and identify the amounts and dates that need follow-up before buying or selling. Proposed 2027 tax notices and hearing dates were checked November 15, 2026. Homestead guidance retains its October 26 check; the rest of the guide retains its September 22 review.
At a glance
Guide highlights
- Label every figure by document type and year.
- Keep estimated market value, taxable market value, and sale price separate.
- Check Plymouth special assessments as well as the county tax statement.
- Use actual records and closing allocations, not a citywide tax percentage.
- Recent buyers should confirm homestead classification and applicable December 31, 2026 requirements with the county assessor.
01
Find the parcel before comparing any numbers
Use Hennepin County’s property information search to identify the home by address or property identification number. Check the parcel and unit carefully, especially where a property has a similar street address, separate lot, or association structure. Save the tax statement and valuation information with the lookup date, rather than copying an unlabeled number from a listing.
Make one folder for each address under consideration. Put the street address, parcel number, document title, assessment year, and taxes-payable year on the first page. If a listing and county record disagree, keep both and ask what accounts for the difference. A newer date, different tax year, or different field can explain a mismatch; an unexplained discrepancy should remain an open question.
02
Estimated market value is a dated assessment
Minnesota Revenue explains estimated market value as the assessor’s estimate of an ordinary open-market sale value. Assessors use comparable sales and mass-appraisal methods. It is part of the property-tax process, not a current offer from a buyer or a guarantee of a later sale price. A home’s characteristics and the market can change between the assessment date and your transaction.
Hennepin County’s assessment calendar sets the valuation date at January 2. The year on the assessment matters: January 2, 2026 assessment information is used for taxes payable in 2027. For a sale-price discussion, pair the records with current comparable sales through a Plymouth home-value review, keeping the purpose and date of each figure clear.
03
Taxable market value is a different field
Minnesota Revenue’s property-tax explanation says estimated market value is adjusted for applicable exclusions, deferments, or reductions to determine taxable market value. Classification reflects property use and also enters the tax calculation. A lower taxable value does not mean a seller must accept that amount for the home, and equal asking prices do not establish equal tax bills.
Homestead check, October 26, 2026: If you bought or began occupying a Plymouth home in 2026, confirm its homestead classification with Hennepin County rather than assuming the seller’s classification transfers. The county’s homestead page lists December 31, 2026 as the deadline and says residential applicants must own, occupy, and apply by December 31. Minnesota Revenue explains that applications go to the county assessor by December 31 for taxes payable the following year—2027 for this application cycle.
Once homestead is granted, Revenue says routine annual reapplication is unnecessary, although the assessor may request another application or supporting documents. Check required updates when ownership or occupancy changes. Special ownership or occupancy situations and other tax programs need their own official review; this deadline does not establish eligibility or a particular tax reduction. Do not subtract a seller’s refund or deferral from your own projected bill.
04
Read the tax year and document type together
The county’s annual tax timeline separates assessment, budgeting, proposed taxes, and the final bill. Valuation information arrives in the spring for the following year’s taxes; proposed levies and tax notices generally follow in November, and the next year’s final tax statements arrive in March. Proposed taxes are part of the budget process, not the final amount due.
Keep the current statement labeled taxes payable 2026, the valuation notice 2026 assessment / payable 2027, and the November notice proposed taxes payable 2027. Minnesota Revenue’s November 12 update says the mailed November notice estimates 2027 taxes for the parcel. Hennepin County explains that the estimate excludes special assessments that may appear on the final bill.
Hearings on proposed 2027 taxes, checked November 15, 2026: The county’s Truth in Taxation schedule lists Hennepin County’s meeting for December 1, 2026 at 6 p.m. at the Government Center, and Plymouth’s for December 8, 2026 at 7 p.m. at City Hall, 3400 Plymouth Boulevard. Use the meeting information on the parcel notice and check the organizer’s latest schedule before going. These meetings take public comment on proposed budgets and levies. Follow the valuation notice separately for an assessment appeal.
05
Check city special assessments separately
Plymouth’s special-assessment page explains that assessments can finance property-benefiting improvements, including street, water, sewer, and sidewalk work. They can also recover certain unpaid charges. The City directs owners to its property-information tool for parcel-specific information. This is a separate check from simply reading the property’s estimated market value.
For a contemplated sale, ask the City and closing professional which assessment items are already on the tax statement, whether another balance or pending item requires investigation, and what a dated payoff would include. Record principal, interest, status, and the as-of date when supplied. Do not enter an annual installment and the same obligation’s full payoff twice in a proceeds estimate.
06
Separate a payment deadline from closing allocations
As reviewed September 22, 2026, Hennepin County’s payment guidance gives May 15 and October 15 as the regular property-tax payment dates, shifting to the next business day when a date is a weekend or holiday. Check the actual statement and payment method. Special classifications and small tax bills have different rules in the state guidance; this is not a universal calendar for every property.
If a sale closes near a due date, confirm whether the owner, mortgage servicer, or closing professional will make the payment and how it will be credited. A contract’s allocation between buyer and seller is a different question from the county’s due date. Ask for a written explanation on the settlement worksheet rather than assuming a monthly escrow withdrawal proves the county received payment.
07
Use this comparison worksheet for two Plymouth homes
Create two columns with matching document years. For each home record the parcel, estimated market value, taxable market value, classification, current taxes payable, payment status, and separately identified assessments. Then add the questions still awaiting confirmation. Do not rank the homes by a single tax number while one column contains a prior-year bill or an unverified exclusion.
Add ownership expenses outside this worksheet—insurance quotes, association dues, utilities, and maintenance—on separate lines. The moving-to-Plymouth guide covers broader location research. School districts are also address-specific; use the school district lookup guide for enrollment questions, rather than treating a tax line as proof of an individual school assignment.
Swipe across to read the full table →
| Field | Home A | Home B |
|---|---|---|
| Parcel and unit | Confirm exact parcel | Confirm exact parcel |
| Assessment / payable year | Record both years | Record both years |
| Estimated / taxable value | Keep separate amounts | Keep separate amounts |
| Classification and programs | Confirm actual record | Confirm actual record |
| Current bill and paid status | Attach statement and status | Attach statement and status |
| City assessments | Record balance, status, date | Record balance, status, date |
| Unresolved question | Name office and follow-up date | Name office and follow-up date |
08
Send the question to the right office
For value, property characteristics, or classification questions, start with the assessor contact on the valuation notice. For payment posting, balances, or a tax-statement question, contact county property-tax staff. For Plymouth special assessments, use the City contact on its assessment page. For closing prorations and payoff treatment, ask the professional preparing the settlement statement.
Hennepin County directs owners to their valuation notice for appeal options and dates. Investigate an apparent record error promptly and follow the deadline printed on the notice. Sellers can connect the resulting documents to the selling plan and selling-cost worksheet. Parcel-specific amounts and personal tax outcomes still require direct confirmation.
Planning note
A clear property folder should show which year every number belongs to and which office confirmed it. That makes tax records useful to a move without turning one owner’s bill into a promise for the next owner.
Keep your Plymouth research moving
Build your property-specific selling plan.
Use these related guides to organize the remaining questions, then talk through the details of a specific home.
Frequently asked questions
I bought a Plymouth home in 2026. What should I check before year-end?
Is Plymouth’s assessed value the same as my home’s sale price?
Why is taxable market value lower than estimated market value?
Does a 2026 assessment describe taxes payable in 2026?
Is the November proposed tax notice my 2027 bill?
Where do I check Plymouth special assessments?
Will I pay exactly the seller’s current property tax bill?
Who handles a property-value dispute?
Sources and verification
These are the public sources used for facts that can change. For an address-specific decision, verify the current details before you act. Read our research standards.
- Hennepin County — homestead deadline and application requirements, checked October 26, 2026
- Minnesota Department of Revenue — homestead classification and reapplication, checked October 26, 2026
- Hennepin County — property information search
- Hennepin County — assessment and assessment-year calendar
- Minnesota Department of Revenue — estimated market value
- Minnesota Department of Revenue — understanding property tax
- Hennepin County — property taxes overview
- Minnesota Department of Revenue — proposed taxes payable 2027, published November 12, 2026
- Hennepin County — property notices, checked November 15, 2026
- Hennepin County — 2026 Truth in Taxation meeting schedule, checked November 15, 2026
- City of Plymouth — special assessments
- Hennepin County — property tax payment dates and methods
- Minnesota Department of Revenue — property tax information and programs
Written by
Bryce CaldwellBryce Caldwell is a RE/MAX Results agent who knows the Lake Minnetonka corridor and the Twin Cities west metro. Full-time since 2022 with a 5.0 Zillow rating across 27 reviews, he gives buyers and sellers honest, no-pressure guidance — and writes these guides.
Keep reading
Keep exploring Plymouth
 Photo: McGhiever · CC BY-SA 4.0
Schools / 8 min read
5 Plymouth Elementary Schools to Compare Before You Move
Compare five named Plymouth elementary schools by classroom approach, school-day timing, care, and enrollment—with useful questions for each visit.
Read the guidePhoto: McGhiever · CC BY-SA 4.0Local life / 6 min read
5 Things to Do in Plymouth on a Rainy Day
Swap a washed-out outdoor plan for a library browse, indoor playground, movie, public skate or Urban Air visit at five Plymouth locations.
Read the guide Illustration: OpenAI image generation · Generated asset
Food & drink / 7 min read
5 Plymouth Restaurants for a Date Night Worth Planning
A music-room dinner, inventive cocktails, a shared Indian feast, Thai comfort food, or thin-crust pizza: five different ways to make an evening in Plymouth.
Read the guide